TD SYNNEX top line soars as distributor outperforms European market
The distributor expects continued organic growth while M&A remains “at the core” of its strategy
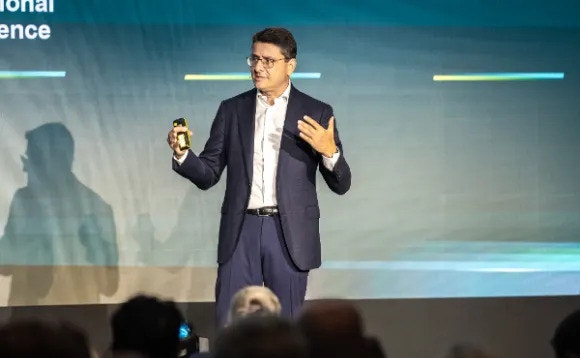
US-based distie TD SYNNEX has shared strong Q1 results, driven by refresh cycles and supply chain services.
Top line soared 18.1 per cent to $17.2bn (£12.9bn), up from $14.5bn in the same period last year.
Net income leapt 61.2 per cent to $383m.
The organisation reported strong performance in Europe, where its distribution business rose at a double-digit rate, ahead of the broader market, which grew at mid-single digits.
“We’re very well positioned in all the key markets in Europe,” said CEO Patrick Zammit.
“We have a strong pan-European presence.”
He added the firm is benefiting from exposure to faster-growing markets such as Poland and Spain.
TD SYNNEX said it continues to gain share across the region, supported by its end-to-end portfolio and vendor roster.
AI demand, pricing and supply chain services drive growth
The distributor highlighted AI as a key driver across multiple product categories, particularly PCs and servers.
Zammit said demand for AI-enabled devices is increasing as organisations begin deploying AI workloads more broadly.
“End users have now defined their use cases. They are starting to build their AI factories, and that’s driving demand in the market,” he said on an earnings call.
He also pointed to continued momentum in PC refresh cycles, with an evolving mix of AI PCs set to support demand in coming quarters.
“The refresh is not over, [which] continues to be a tailwind for us.
“The other aspect is that the weight of AI PCs continues to increase.
“One of the drivers for it is that you will have more and more AI applications running at the edge, so having an AI PC is going to become more and more important in companies.”
He also said pricing increases across hardware categories are expected to support revenue growth, even as concerns remain around potential demand softness.
CFO David Jordan added that demand remains strong across both distribution and Hyve, although pricing impacts will take time to flow through into financial results due to backlog cycles.
“We have a lot of revenue that is back-to-back, meaning it’s built, put into a backlog, and might take two to five months to ship.
“It’s not like you’re going to see a massive spike in our P&L immediately from price increases.”
Zammit explained that while some demand pressure could emerge later in the year, higher average selling prices are likely to offset any decline in unit volumes.
Supply chain services grew more than 100 per cent year-on-year, driven by customer demand to manage inventory amid pricing volatility.
The CEO cautioned that the segment is more volatile than the rest of the business, with momentum likely to depend on market conditions.
Hyve and large hyperscalers
The group operates across four reportable segments, including three units related to its IT distribution business within the Americas, Europe and APJ, as well as Hyve Solutions.
Hyve, which designs and deploys customised datacentre infrastructure, reportedly was a major growth driver during Q1.
Zammit said growth was largely driven by the company’s two largest US-based hyperscalers, although diversification is beginning to take shape.
“The diversification has started, but the ramp-up of the programmes we won is going to take a little bit of time.
“We believe we will see the impact of that ramp-up towards the end of fiscal year ’26 and into ’27.”
M&A targets and Q2 projections
Zammit said acquisitions remain a key part of its growth strategy, focusing on geographic expansion, vendor coverage and capability building.
He added the company is evaluating multiple opportunities across regions while maintaining strict valuation discipline.
“M&A is at the core of the strategy.
“It is a way to accelerate execution by geography, technology, or by acquiring vendors we are missing in certain markets.
“We are looking at several opportunities across all regions.
“Our objective is to ensure the price we pay delivers the right return within two years.”
For Q2, TD SYNNEX expects revenue of between $16.1bn and $16.9bn.
Net income is set to reach $234m to $274m.
The company said demand remains strong heading into the next quarter, supported by AI-driven infrastructure investment, PC refresh cycles and continued hyperscaler momentum.